Hard Money Loan New Jersey
OfferMarket Loans
Check your rate
60 seconds · no credit pull
Last updated: May 19, 2025
At OfferMarket, our mission is to empower real estate investors across New Jersey to build generational wealth through property investment. Whether you're flipping brownstones in Jersey City, renovating rentals in Newark, or transforming suburban homes in Cherry Hill, we’ve built an all-in-one platform to support your journey:
💰 Private lending
☂️ Insurance rate shopping
🏚️ Off-market properties
Our Hard Money Loan program is engineered to deliver fast, reliable, and cost-effective capital for purchasing, refinancing, and improving 1-4 unit residential investment properties throughout New Jersey.
Whether you're planning to flip your project in Bergen County for a tidy profit or refinance your Union County rental into a DSCR loan, we’re excited to work with you and be a part of your success.
Let’s dive into the OfferMarket Hard Money Loan Program in New Jersey!
What is a hard money loan?

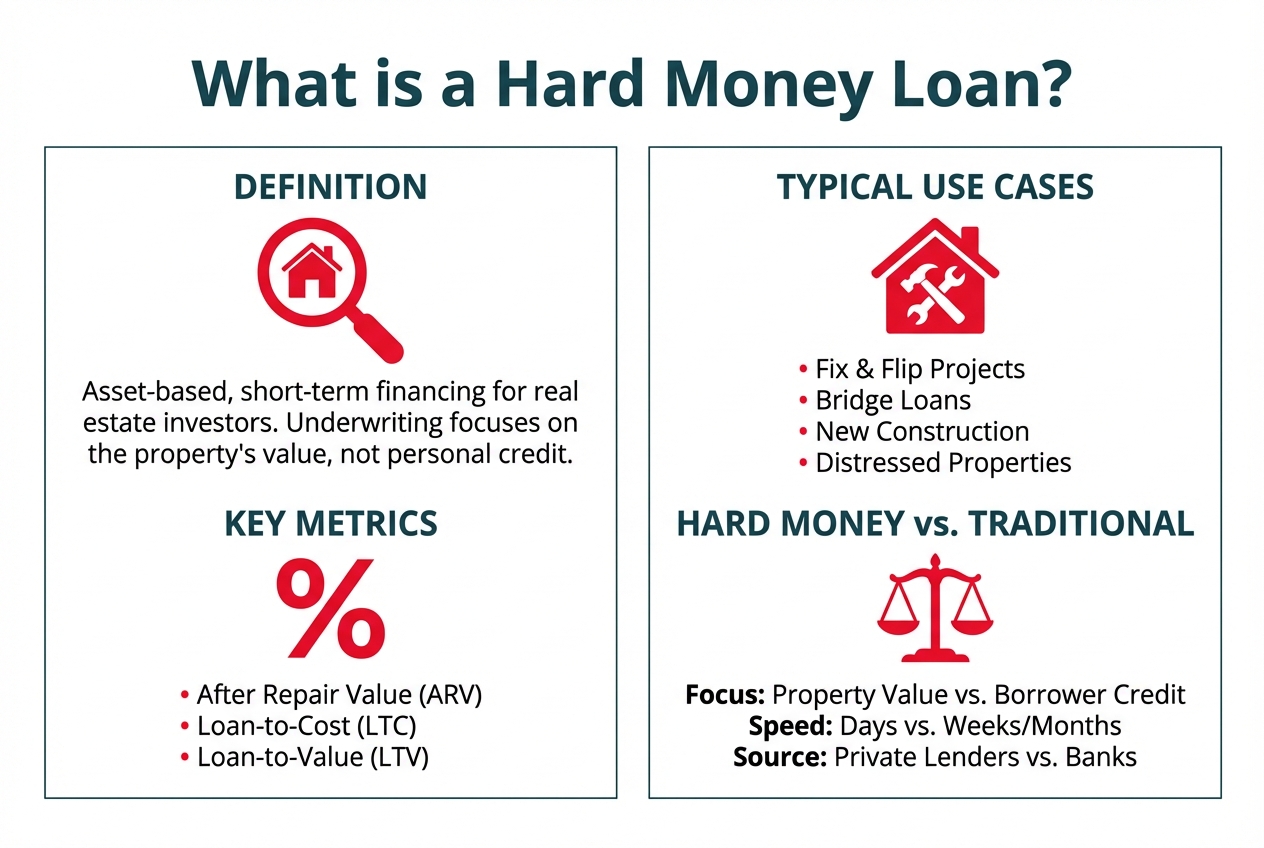
A hard money loan is a short-term real estate investment loan secured by a tangible asset—typically a 1-4 unit residential property. These loans are used to buy, rehab, and either sell or rent the property. In New Jersey’s competitive real estate landscape, hard money loans are a powerful tool for securing fast funding when conventional options fall short.
Often called “bridge loans” or “fix and flip loans,” these financing options are especially useful in fast-moving markets like the New York metro area, where timing can make or break a deal.
Hard money loan scenarios in New Jersey
Real estate investors across New Jersey frequently use hard money loans in the following situations:
- Purchase and renovate a distressed or outdated property – for example, rehabbing an older duplex in Trenton or a boarded-up home in Paterson without tying up your own cash
- Refinance a distressed or outdated property purchased with cash and then renovate the property – such as picking up an off-market foreclosure in Camden and needing to access funds to complete the rehab
- Refinance an existing loan on a distressed or outdated property and then complete the renovation – maybe your original lender needs to be repaid but your Clifton property still requires finishing touches
- Purchase a property with no intention of rehabbing the property – like acquiring an undervalued townhouse in Elizabeth to resell it in its current condition
- Refinance a cash purchase with no intention of rehabbing – perhaps you've picked up a deal in Passaic and want to tap your equity for another project
- Refinance an existing loan with no intention of rehabbing – rehab is done on your Atlantic City property but you need more time before you exit via sale or refinance
How it works
A hard money loan consists of two primary funding components:
- Initial Advance – This portion of your loan goes toward the property purchase price. At closing, this amount is wired directly to the title company handling your New Jersey transaction.
- Construction Holdback – This portion is allocated to your renovation budget. Funds are disbursed to you through draw requests based on completed rehab milestones.

Hard money loans are built for flexibility. You can choose to leverage only the initial advance or only the construction holdback—whatever suits your investment strategy in the Garden State. Most investors throughout New Jersey, from South Orange to Atlantic Highlands, utilize both to maximize leverage and reduce out-of-pocket expenses.
Some investors prefer to self-fund renovations, especially in simpler cosmetic projects or when tight timelines matter. Others purchase properties with cash and only need construction financing to complete rehabs on distressed homes in places like Irvington or Vineland.
Your exit strategy might involve flipping the property for profit or holding it as a rental. In New Jersey’s dynamic housing market, many investors pivot mid-project—what starts as a BRRRR (Buy, Rehab, Rent, Refinance, Repeat) play may end up being a flip due to favorable resale prices, especially in demand-heavy neighborhoods like Montclair or Hoboken.
Likewise, if the resale market softens, converting your investment into a rental with a DSCR refinance can help you ride out the dip and generate cash flow. That’s why choosing projects with dual exit strategy potential is critical for success in NJ’s fluctuating market conditions.
Who uses hard money loans in New Jersey?
New Jersey’s active investor community uses hard money loans for a range of strategies:
Fix and flip investors
Local flippers rely on fast access to capital for acquiring and improving distressed homes throughout cities like Newark, East Orange, and Asbury Park.
Rental property investors (BRRRR)
Landlords looking to build long-term rental portfolios in areas like Middlesex County or Gloucester County utilize our Fix and Rent bundle: a hard money loan for the purchase and rehab, followed by a discounted DSCR loan for the refinance.
In practice, many of our New Jersey clients take a hybrid approach—flipping some properties, holding others, and staying flexible depending on local trends, zoning, and valuation swings. This adaptability is one of the keys to long-term success across the state.
Hard Money Loan Program Guidelines
Here’s a snapshot of our hard money lending criteria tailored for real estate investors operating across New Jersey:
| Criteria | Guideline |
|---|---|
| Loan amount (minimum) | $25,000 |
| Loan amount (maximum) | $2,000,000 |
| ARV (minimum) | $100,000 |
| Experience | Not required |
| Credit score (minimum) | 680 |
| Borrowing entity | LLC or Corporation |
| Initial advance | up to 90% |
| Construction holdback | up to 100% |
| LTARV (maximum) | 75% |
| Interest rate | get instant quote |
| Origination fee | 1.5 to 2 points |
| Term | 12 to 24 months |
| Points out | None |
| Prepayment penalty | None |
| Structure | Interest-only with balloon payment |
| Recourse | Full (51% of borrowing entity must guarantee) |
| Exit strategy: Sale | minimum 30% ROI |
| Exit strategy: Refinance | minimum 1.1 DSCR after repairs |
| Valuation | Appraisal report or In-house valuation |
| SqFt (minimum) | Single family: 700+; 2-4 unit: 500+ per unit; Condo: 500+ |
| Acreage (maximum) | 5 acres |
| Interest accrual | Under $100,000 loan: full boat; $100,000+ loan: as disbursed |
| Advanced draws | Lender discretion |
| Down payment (minimum) | $10,000 |
Project Eligibility in New Jersey
Our commitment to New Jersey real estate investors centers on sustainable growth and sound risk management. We take pride in maintaining one of the lowest default rates in the industry—less than 0.5%. That means we’re not just a lender—we’re your strategic partner.
While experience is not required, first-time investors in New Jersey are advised to start with light or moderate rehab projects. High-risk, extensive renovations in areas like Camden or deep rural parts of Sussex County may face additional scrutiny, especially during periods of market volatility.
Our role is to protect your interests, offering guidance that keeps your projects on budget and on schedule. That includes evaluating your scope of work and ensuring you meet eligibility requirements tied to rehab complexity.
Initial Advance
In New Jersey markets—from suburban Morris County to urban Essex County—your initial advance is shaped by a combination of your credit profile, experience, and property specifics. Here’s how we calculate it:
Minimum credit score: 680 (720+ preferred for max leverage)
Experience tiers: We reward seasoned investors with higher leverage
Professionals: Licensed Realtors, GCs, and Engineers may qualify for increased initial advances
Valuation limit: If the purchase price exceeds As-Is value, your advance will be capped based on the lower number
Exit strategy influence: For flips, a projected ROI of 30%+ and profit of $15K+ is required. For rentals, we target at least a 1.1 DSCR post-repair.
Rural properties in areas like Warren or Salem Counties come with reduced leverage and a minimum experience tier of 3 due to increased risk.
Experience-Based Tiers
| Tier | Verifiable Experience |
|---|---|
| 1 | 0 |
| 2 | 1 to 2 |
| 3 | 3 to 4 |
| 4 | 5 to 9 |
| 5 | 10+ |
Initial Advance by Tier
| Tier | % of Purchase Price |
|---|---|
| 1 | 80%* |
| 2 | 85% |
| 3 | 85% |
| 4 | 90% |
| 5 | 90% |
* 85% available as an exception for borrowers with exceptional credit and liquidity.
Adjustments to Initial Advance
| Scenario | Adjustment |
|---|---|
| Credit score under 720 | -5% |
| Full gut renovation | -5% |
| New market (i.e., new to New Jersey) | -5% |
| Licensed Realtor | up to +5% |
| Licensed General Contractor | up to +10% |
| Licensed Professional Engineer | up to +10% |
| Rural area (e.g., Pine Barrens property) | -20% (Tier 3+) |
Rehab Scope Classification
| Scope | Definition |
|---|---|
| Light | Rehab < 25% of purchase price |
| Moderate | Rehab = 25% – 49.99% of purchase price |
| Heavy | Rehab = 50% – 99.99% of purchase price |
| Extensive | Rehab = 100%+ of purchase price or “lopsided deal” |
Rehab Scope Eligibility
| Tier | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Experience | 0 | 1-2 | 3-4 | 5-9 | 10+ |
| Light | Eligible | Eligible | Eligible | Eligible | Eligible |
| Moderate | Ineligible | Eligible | Eligible | Eligible | Eligible |
| Heavy | Ineligible | Eligible | Eligible | Eligible | Eligible |
| Extensive | Ineligible | Ineligible | Eligible | Eligible | Eligible |
LTARV Limits
| Tier | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Experience | 0 | 1-2 | 3-4 | 5-9 | 10+ |
| Light | 70% | 70% | 75% | 75% | 75% |
| Moderate | Ineligible | 70% | 75% | 75%< | 75% |
| Heavy | Ineligible | 70% | 75% | 75%< | 75% |
| Extensive | Ineligible | Ineligible | 70% | 70% | 70% |
LTFC Limits
| Tier | 1 | 2 | 3 | 4 | 5 |
|---|---|---|---|---|---|
| Experience | 0 | 1-2 | 3-4 | 5-9 | 10+ |
| Light | N/A | N/A | N/A | N/A | N/A |
| Moderate | Ineligible | N/A | N/A | N/A< | N/A |
| Heavy | Ineligible | N/A | N/A | N/A< | N/A |
| Extensive | Ineligible | Ineligible | 85% | 90% | 90% |
Example: No Experience – Tier 1
Purchase Price: $100,000
Credit Score: 695
Rehab Budget: $24,000
ARV: $150,000
Initial Advance: $75,000
LTARV: 66%
LTFC: 79.8%
Interest Accrual: Full boat
No Experience, Excellent Credit – Tier 1
Credit Score: 750
Initial Advance: $80,000
LTARV: 69.33%
LTFC: 83.9%
Interest Accrual: As disbursed
Experienced Investor – Tier 4
Experience: 5 completed deals
Initial Advance: $90,000
LTARV: 73.33%
LTFC: 91.67%
Interest Accrual: As disbursed
Refinance Using As-Is Value Instead of Cost Basis
In New Jersey, it’s common for seasoned investors to enhance the value of their properties significantly over time. If your property—perhaps a rental held for years in New Brunswick or a duplex in Hackensack—is now worth more than your original cost basis, we may underwrite based on the As-Is market value.
This allows you to tap into more leverage and reinvest into new opportunities. However, to qualify, the following must be true:
The property must be habitable (C4 condition or better)
Property must be seasoned for at least 3 years
Payoff statement must show no default charges, extensions, or late fees
Credit score must be 680 or higher
Experience Tier must be 3 or greater (4+ verifiable similar rehab projects)
Comparable recent sales in the neighborhood must support the As-Is valuation
Scenario must support the new leverage request (e.g., long-term rental recently vacated, now being renovated for resale)
Wholesaler Transaction Guidelines
Wholesaling is active throughout New Jersey, particularly in distressed inventory zones. OfferMarket supports deals involving assignment fees or double-close strategies—provided the markup is reasonable and clearly documented.
| Example |
|---|
| A-B Contract (owner & wholesaler): $100,000 |
| B-C Contract (wholesaler & investor): $125,000 |
| As-Is Value: $125,000 |
| Value basis for initial advance: $120,000 (cap at 20% markup) |
Key guidelines:
Max 20% markup allowed between A-B and B-C contracts
Transaction must be arm’s length
Full contract chain required (A-B, B-C, assignment agreements)
MLS-listed properties may void eligibility for financing markup
No funding for finder/referral fees
Wholesaler’s operating agreement must be submitted
Construction Holdback
For projects in cities like Perth Amboy or Woodbury, construction holdbacks offer essential liquidity relief. Instead of pulling funds from your own capital, we reimburse you for completed scope milestones.
| Draw Guidelines | Details |
|---|---|
| Minimum draw amount | None |
| Maximum draw amount | Up to 100% of remaining holdback |
| Materials delivered (not installed) | 50% reimbursement (with receipts) |
| Draw inspection | App-based (self-serve) |
| Draw turnaround | 0 to 2 business days |
| Draw fee | $270 |
| Wire fee | $30 |
If you have ample liquidity and prefer not to use construction financing, you may elect to proceed with initial advance only.
Appraisal and In-House Valuation
Every New Jersey hard money loan requires a property valuation. We’ll determine the most appropriate method based on your credit, experience, location, and loan terms.
In-House Valuation Eligibility
| Requirement | Guideline |
|---|---|
| Property type | SFH, Duplex, Triplex, Quad |
| Tier | 4 or higher |
| Credit Score | 720+ |
| Rural Property | Not allowed |
| New Market | Not allowed |
| Max LTARV | 70% |
Even when eligible, we may still require an appraisal at our discretion.
Exterior Appraisal
Accepted for New Jersey transactions that involve:
REO purchases
Foreclosure or sheriff’s sale
Online or bankruptcy auctions
Must be dated within 120 days of closing. If 120–179 days old, recertification is required.
Interior Appraisal
Required for all other scenarios, including traditional purchases or refinances not covered above.
| Property Type | Forms Required |
|---|---|
| Single Family | 1004 + 1007 ARV with As-Is (non-gridded) |
| 2–4 Unit | 1025 + 216 ARV with As-Is (non-gridded) |
| Condo | 1073 + 1007 ARV with As-Is (non-gridded) |
Appraisal Transfer
We accept third-party appraisals if the following are provided:
Ordered via approved AMC
Appraisal is under 180 days old
Re-certification if over 120 days
Signed AIR-compliant transfer letter
PDF and XML appraisal files
Paid appraisal invoice
Stabilized Hard Money Loan
If your property is turnkey (appraisal condition rating of C4 or better), we can lend up to 75% of its As-Is value.
| Criteria | Guideline |
|---|---|
| LTV (maximum) | Tier 1: 70% Tier 2: 70% Tier 3: 75% Tier 4: 75% Tier 5: 75% |
| LTFC (maximum) | Tier 1: 80% Tier 2: 80% Tier 3: 90% Tier 4: 90% Tier 5: 90% |
| Appraisal condition rating | C1, C2, C3 or C4 |
| Loan Term (maximum) | 12 months |
This is ideal for finished rental properties in areas like Plainsboro or Princeton.
Key Loan Details
| Criteria | Details |
|---|---|
| Loan Amount | $25,000 to $2,000,000 |
| Units per Property | 1 to 4 |
| Property Types | Non-owner occupied SFR, 2–4 unit, Condo |
| Min SqFt | SFR: ≥700; 2–4 unit and Condo: ≥500/unit |
| Max Acreage | 5 acres |
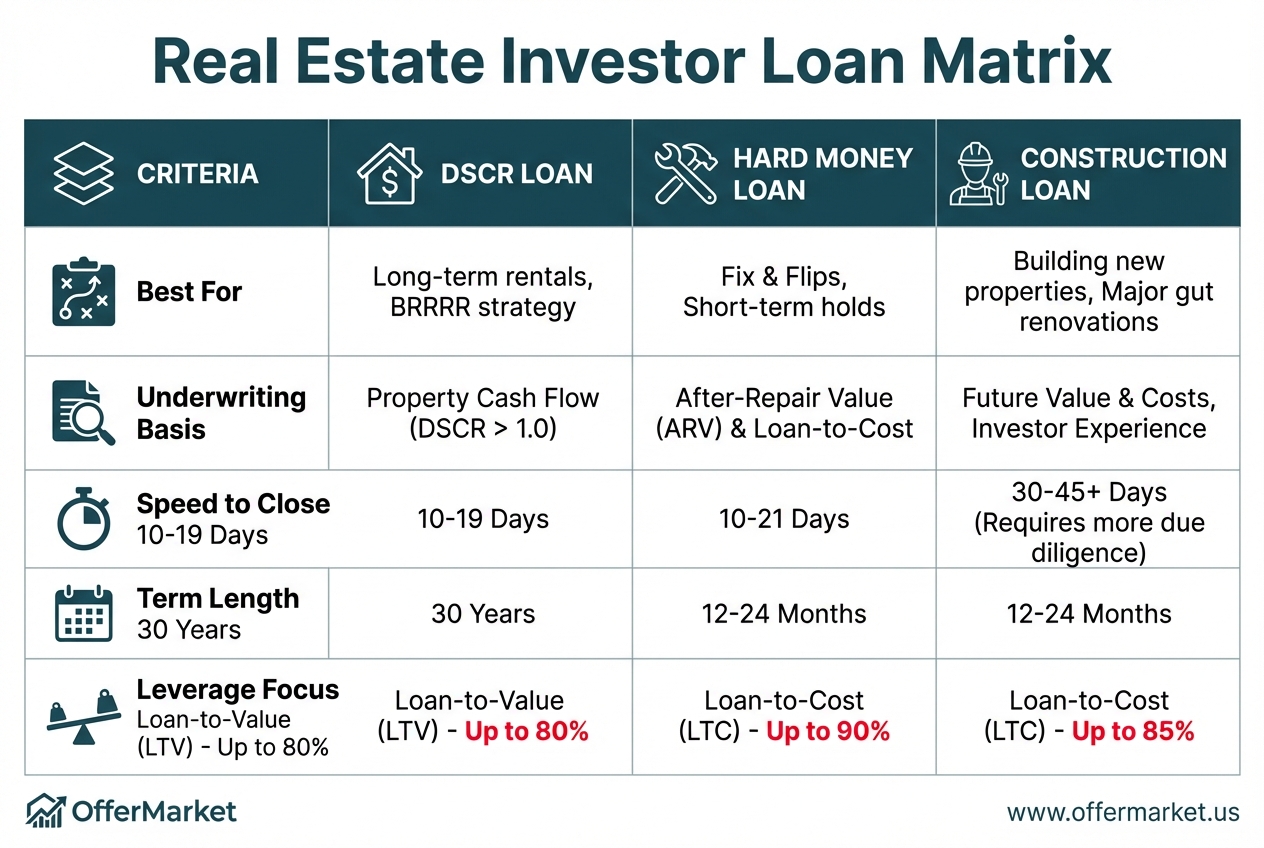
| LTC | Up to 90% purchase, 100% rehab |
| LTARV | Up to 75% |
| Term | 12 months (up to 24 for select projects) |
| Extensions | Up to 50% of original term |
| Points | 1.5–2% (min $2,000) |
| Prepay Penalty | None |
| Occupancy | Business use only |
| Transaction Types | Purchase, Refi |
| Geographic Region | All NJ counties |
| Amortization | Interest-only with balloon |
| Interest Accrual | Full boat < $100K; As disbursed ≥ $100K |
Extensions
Our loans are structured for 12–24 month payoff timelines. Extensions should be the exception, not the rule.
To avoid needing extensions:
Choose experienced GCs
Avoid heavy rehab relative to skill level
Avoid delayed permitting markets (e.g., Jersey Shore)
Secure access to property (no holdovers)
Prioritize deals with dual exit strategies
Extension Limits
| Initial Term | Max Extension |
|---|---|
| 12 months | 6 months |
| 18 months | 9 months |
| 24 months | 12 months |
Extension Terms and Fees
| Extension Term | Fee |
|---|---|
| 3 months (1st) | 1% of loan amount |
| 3 months (2nd) | 1.5% of loan amount |
| 6 months (1st) | 2.5% of loan amount |
Extension Prerequisites
You must confirm active builder’s risk insurance coverage for the entire extension period before approval.
Ineligible Property Types
Hard money loans are not available for the following in New Jersey:
Mixed-use or 5+ unit multifamily
Co-ops, condotels, mobile homes
Farms, ranches, cabins
Properties on unpaved roads
Luxury/unique homes
Vacation rentals
Commercial property
Exception Scenarios
In certain NJ cases, exceptions may be granted with additional documentation:
Credit score 660–679
Leasehold land
Small SFR (500–699 sq ft)
Small 2–4 unit (400–499 sq ft/unit)
Initial advance based on As-Is value
Non-arms-length deals
Financed interest
Stabilized refinance with strong comps
Borrower and Guarantor Requirements
Our lending standards are designed to promote responsible borrowing while enabling real estate investors across New Jersey to scale with confidence. Here's what you need to qualify:
| Item | Requirements / Eligibility |
|---|---|
| Borrowing Entities | LLC or Corporation only (nonprofits are ineligible) |
| Eligible Borrowers | US Citizens, Permanent Residents, and qualifying Foreign Nationals |
| Foreign Nationals | Valid passport and US Visa (student/travel visas excluded); FICO required for guarantors |
| Credit Requirements | Minimum FICO 680 (exceptions down to 660 considered); Tri-merge credit report (≤ 120 days old) |
| Additional reserves if < 5 tradelines | |
| Liquidity Requirements | Must have estimated cash to close + 25% of rehab budget |
| Acceptable assets: personal/business bank or brokerage accounts, retirement (50% haircut) | |
| Verification: Two most recent statements, LOE for large deposits | |
| Guaranty Structure | Purchase: ≥51% of entity must guarantee; Refi: 100% must guarantee; Full recourse required |
| Net Worth Requirement | Combined guarantor net worth must be at least 50% of the loan amount |
Liquidity Verification
We verify liquid assets to ensure borrowers have the financial buffer needed for successful project execution.
Eligible Accounts:
Personal or business bank accounts
Business brokerage accounts (with operating agreement verification)
Retirement accounts (50% of balance counted)
No need to move funds. Verification is based on most recent statements—no minimum seasoning period required.
Credit and Background Items
We carefully assess credit health to maintain New Jersey’s low default environment:
Use middle score of 3 or lower of 2 scores
Require 6 months of interest reserves if:
No mortgage tradelines
Fewer than 5 tradelines
Bankruptcy < 7 years
Foreclosure < 7 years
Late mortgage payments require LOE
Past due tradelines must be resolved before funding
Civil lawsuits: LOE required, subject to discretion
Criminal lawsuits: ineligible
Financial/serious crimes: ineligible
Interest Reserves
Interest reserves protect your liquidity and may be required based on credit tier and risk indicators.
| Guarantor Scenario | Interest Reserve Requirement |
|---|---|
| FICO 700+ | 1 month |
| FICO 660–699 or concern on report | 3–6 months |
| High experience or strong profile | 0 months (at lender discretion) |
Financed Interest Payments
To conserve your working capital, you may qualify to finance your interest payments.
Example:
Loan amount: $100,000
Interest rate: 12%
Term: 9 months
Accrued interest: $9,000
No monthly payments—interest due at payoff
This is especially useful in high-cost areas like Bergen or Hudson Counties where capital flexibility matters.
Property Sourcing Guidelines
To expedite approval and protect against risk, ensure the following are submitted:
Purchase contracts, settlement statements
Payoff letters, entity documents, and ID
Detailed rehab scope
Track record documentation
If new to NJ, include GC agreement or LOE
Wholesale deals require contract chain and justification
Structural rehab may require engineer/architect approval
Insurance Guidelines for NJ Hard Money Loans
Builders Risk or Fix and Flip insurance is required. Install smoke detectors and security systems immediately after closing to stay compliant.Coverages and Limits
This outlines the required types of coverage and their respective minimum policy limits:
| Coverage Type | Limit | Required |
|---|---|---|
| Dwelling | Replacement Cost or Loan Amount (zero coinsurance) | Yes |
| Liability | $1M per occurrence / $2M annual aggregate | Yes |
| Builder’s Risk | Included | Yes |
| Flood | Greater of $250,000 or loan balance (if in flood zone) | Only if in FEMA SFHA |
Coverage Details
This outlines specific policy requirements and restrictions for approved insurance providers and documents:
| Coverage Item | Requirement |
|---|---|
| AM Best Rating | A- VIII or greater |
| Policy Type | Special Form |
| Deductible | $1,000 to $5,000 |
| Lender’s Designation | Mortgagee and Additional Insured |
| Exclusions | No windstorm, hail, or named storm exclusions |
| Cancellation Notice | 30-day notice required |
Frequently Asked Questions About Hard Money Loans in New Jersey
What states does OfferMarket fund hard money loans?
- Arizona*
- Alabama
- Arkansas
- California
- Colorado
- Connecticut
- Delaware
- Florida
- Georgia
- Hawaii
- Idaho
- Illinois
- Indiana
- Iowa
- Kansas
- Kentucky
- Louisiana
- Maine
- Maryland
- Massachusetts
- Michigan
- Mississippi
- Missouri
- Minnesota*
- Montana
- Nebraska
- Nevada*
- New Hampshire
- New Jersey
- New Mexico
- New York
- North Carolina
- North Dakota*
- Ohio
- Oklahoma
- Oregon
- Pennsylvania
- Rhode Island
- South Carolina
- South Dakota*
- Tennessee
- Texas
- Utah
- Vermont*
- Virginia
- Washington
- Washington DC
- West Virginia
- Wisconsin
- Wyoming
(*) In states where NMLS license is required for business purpose lending or we do not directly lend, OfferMarket operates as a rate shopping service and refers your loan to a licensed capital provider.
Does OfferMarket provide hard money loans in New Jersey?
Yes, we proudly serve investors across the entire state of New Jersey—from Jersey City brownstones to South Jersey duplexes. Whether you're investing in Essex County, Mercer, Monmouth, or Camden, OfferMarket offers fast and flexible hard money loans tailored for your success in the Garden State.
Can I take out more than one hard money loan at the same time?
Absolutely. Many of our New Jersey clients manage multiple simultaneous projects, especially in competitive areas like Union County and Passaic County. However, we assess each borrower's liquidity, cash flow, and project bandwidth to ensure they're not overextended.
If we see that your resources may be stretched too thin, our risk team will collaborate with you to prioritize sustainable growth without jeopardizing your portfolio or credit.
Are hard money loans considered commercial financing?
Yes. All hard money loans from OfferMarket are business-purpose loans. They’re issued to a legal business entity such as an LLC or corporation, not to individuals.
This classification means your loan is treated as commercial financing, with requirements and benefits aligned with investment use rather than personal occupancy.
What’s the minimum loan amount I can borrow?
The smallest hard money loan we issue is $25,000. This accommodates New Jersey’s diverse markets—from entry-level flips in small towns to larger projects in high-cost neighborhoods like Montclair or Westfield.
What types of properties are eligible?
Our program supports a wide range of residential investment properties in New Jersey:
Single Family Homes (SFRs)
2–4 unit multifamily buildings
Townhomes
Warrantable condominiums
Planned Unit Developments (PUDs)
Important exclusions:
We do not fund:
Mixed-use buildings
5+ unit multifamily
Condotels, co-ops, mobile/manufactured homes
Commercial or agricultural properties
Cabins, log homes, or luxury estates
Properties on dirt/unpaved roads
Vacation or seasonal rentals
How is Loan-to-Value (LTV) calculated?
For New Jersey hard money loans, we generally focus on Loan-to-After-Repair Value (LTARV), which factors in your projected ARV. Here’s how it breaks down:
LTV: Based on the lesser of As-Is market value or purchase price
LTARV: Total loan amount (purchase + rehab) divided by the ARV determined via appraisal or in-house valuation
This dual valuation method ensures responsible lending, especially important in high-variance NJ submarkets.
What are the minimum credit requirements?
A 680 FICO score is our baseline requirement for all guarantors. In some cases, we may consider scores down to 660, but this will require stronger liquidity and additional reserves.
We focus on the guarantors of the borrowing entity, not passive members or non-signing investors. The credit profile helps us determine interest reserves, leverage limits, and overall loan structure.
Do I need prior real estate investing experience?
No prior experience is required—but it helps.
We assess your track record to determine your experience tier (0–5). More experience means higher leverage and more flexible rehab scopes. However, we work with new investors in New Jersey all the time, especially those getting started in BRRRR or fix and flip projects.
For first-time investors, we typically recommend focusing on light-to-moderate rehabs in stable, high-demand areas like Middlesex or Burlington Counties.
Can being a wholesaler count toward my experience level?
No. Wholesale transactions do not qualify as verifiable experience.
To be considered experienced, you must have had financial responsibility for completing the rehab and the project’s outcome. Wholesaling, while valuable for sourcing deals, doesn’t meet this standard because you’re not exposed to construction or holding risk.
What documentation will I need to provide?
Required Documentation for Purchase Transactions
| Loan File Section | Required Document |
|---|---|
| Purchase | Fully executed purchase contract (buyer + seller) |
| Credit Report | Soft tri-merge report for all guarantors |
| Background Report | Required for all guarantors |
| Track Record | Required to determine experience tier |
| ID Verification | Government-issued ID (e.g., driver’s license, passport) |
| Borrowing Entity | Articles of Organization, Operating Agreement, Certificate of Good Standing, W-9 |
| Scope of Work | Detailed rehab budget (used to determine ARV) |
| Appraisal Report | Appraisal ordered and uploaded after invoice is paid |
| Bank Statements | Two most recent statements for each guarantor’s account |
| Letter of Explanation | Required when requested (e.g., for large deposits, late payments, background issues) |
Required Documentation for Refinance Transactions
| Loan File Section | Required Document |
|---|---|
| Settlement Statement | Fully executed by buyer and settlement agent |
| Credit Report | Soft tri-merge report for all guarantors |
| Background Report | Required for all guarantors |
| Track Record | Required to determine experience tier |
| ID Verification | Government-issued ID |
| Borrowing Entity | Articles of Organization, Operating Agreement, Certificate of Good Standing, W-9 |
| Sunk Costs | List of expenses already incurred (purchase, rehab, etc.) |
| Scope of Work | Detailed rehab budget (used to determine ARV and draw requests) |
| Appraisal Report | Uploaded after paying appraisal invoice |
| Bank Statements | Two most recent from each guarantor |
| Letter of Explanation | Provided if requested by underwriting |
Are there Special Requirements for Loans Over $1 Million?
| Criteria | Explanation |
|---|---|
| Experience | Minimum of Tier 3; ideally 4+ similar-sized projects |
| Market Liquidity | At least 3 comparable MLS sales within 2 miles in the last 6 months |
| Credit Score | Minimum 680 with at least 5 tradelines showing 24 months of history |
| Rural Designation | Property must not be flagged as rural by CFPB, USDA, or the appraiser |
| Track Record | Comprehensive documentation required for each guarantor |
Glossary of Key Terms
Understanding the terminology behind real estate financing can make or break your investment strategy. Here’s a glossary of the most important terms you’ll encounter when applying for a hard money loan in New Jersey:
| Term | Definition |
|---|---|
| ADU | Accessory Dwelling Unit — a secondary residential structure on the same lot as the primary home. Common in areas with flexible zoning like Jersey City or Highland Park. |
| Arms-Length Transaction | A transaction between unrelated parties acting in their own self-interest, ensuring fair market pricing. |
| Non-Arms-Length Transaction | A deal involving parties with a personal or business connection that may influence terms or pricing. Requires additional documentation. |
| Initial Advance | The portion of your loan disbursed at closing to cover the property’s purchase price. |
| Construction Holdback | The portion of your loan reserved for rehab expenses. Funds are released in draws as work is completed. |
| Interest Reserves | Funds held in escrow to pay interest during the rehab period, required depending on credit and experience. |
| LOE (Letter of Explanation) | A written statement from the borrower explaining anomalies in credit, background, or liquidity documents. |
| LTC (Loan-to-Cost) | The ratio of your loan amount to the total cost (purchase + rehab). |
| LTFC (Loan-to-Full-Cost) | Used for extensive rehabs where the rehab budget exceeds the purchase price. Ensures borrower has capital in the deal. |
| LTV (Loan-to-Value) | The loan amount as a percentage of the property’s current (As-Is) market value. |
| LTARV (Loan-to-After-Repair Value) | The loan amount divided by the projected value after the rehab is completed. |
| Full Boat Interest | Interest accrues on the total loan amount from day one—even if construction funds haven’t been drawn yet. |
| As Disbursed Interest | Interest accrues only on the funds actually released (i.e., initial advance + completed draw amounts). |
| Lopsided Deal | A scenario where the rehab budget is greater than the purchase price or As-Is value, requiring stricter limits. |
| GC Agreement | A contract with your General Contractor outlining scope of work and timelines. Often required for large rehabs. |
| DSCR (Debt Service Coverage Ratio) | A measure of how well the property’s rental income covers the debt payment. We look for a DSCR of 1.1+ after rehab. |
| PITIA | Principal, Interest, Taxes, Insurance, and Association dues — used to calculate DSCR and affordability. |

Get an Instant Hard Money Loan Quote in New Jersey
OfferMarket Capital LLC is the trusted private lending partner for real estate investors across New Jersey. Whether you're flipping a two-family in Newark or doing a BRRRR on the shore, our streamlined process helps you close quickly and confidently.
Thousands of real estate investors across the U.S. trust OfferMarket for:
💰 Private lending ☂️ Insurance rate shopping 🏚️ Off market properties 💡 Market insights

OfferMarket Loans
Check your rate
60 seconds · no credit pull