Mastering DSCR Loan Closing Costs for Your Investment Property
Last Updated: January 31, 2025

When you're looking to refinance an investment property using a DSCR loan,, understanding the nuances of DSCR loan closing costs is essential. These costs can significantly influence your overall investment strategy and profitability.
This guide provides a thorough exploration of what DSCR loan closing costs involve, how to budget for them, and strategies to manage these expenses effectively, ensuring your investment journey is smooth and successful.
What Are DSCR Loans?
Debt Service Coverage Ratio (DSCR) loans are tailored for investors aiming to finance income-producing properties. Unlike traditional loans that assess your personal income, DSCR loans evaluate the property's ability to generate sufficient income to cover the loan payments. This focus makes DSCR loans an attractive option for real estate investors looking to expand their portfolios without being solely reliant on personal financial metrics.
Key Components of DSCR Loan Closing Costs
Understanding the various components of DSCR loan closing costs is crucial for financial preparedness. Here's a breakdown of the primary costs you can expect:
1. Loan Origination Fees
These fees are charged by the lender for processing your loan application. Typically, they range from 0.5% to 1% of the loan amount. This fee covers the administrative costs involved in evaluating and approving your loan.
2. Appraisal Fees
An appraisal determines the property's market value, ensuring the loan amount is appropriate based on the property's worth. Appraisal fees generally range from $300 to $700, depending on the property's size and location.
3. Credit Report Fees
Lenders will pull your credit report to assess your creditworthiness. This fee usually falls between $30 and $50 and covers the cost of obtaining your credit history.
4. Title Insurance
Title insurance protects against any legal issues related to property ownership, ensuring there are no disputes over the property's title. The cost can range from $500 to $1,500, depending on the property's value.
5. Escrow Fees
Escrow fees cover the services of a neutral third party who manages the funds during the transaction, ensuring all parties meet their obligations. These fees typically range from $300 to $700.
6. Recording Fees
Charged by the local government to record the new property ownership and the mortgage agreement, recording fees usually range from $100 to $250.
7. Survey Fees
A property survey may be required to confirm the property's boundaries and ensure there are no encroachments. Survey fees generally range from $150 to $400.
8. Attorney Fees
Legal fees may be necessary to review the loan documents and ensure everything is in order. These fees can range from $500 to $1,000.
9. Miscellaneous Fees
Other costs may include courier fees, document preparation fees, and other administrative expenses, typically totaling between $100 and $300.
Breakdown of Typical DSCR Loan Closing Costs
| Closing Cost | Estimated Cost |
|---|---|
| Loan Origination Fees | 0.5% - 1% of loan amount |
| Appraisal Fees | $300 - $700 |
| Credit Report Fees | $30 - $50 |
| Title Insurance | $500 - $1,500 |
| Escrow Fees | $300 - $700 |
| Recording Fees | $100 - $250 |
| Survey Fees | $150 - $400 |
| Attorney Fees | $500 - $1,000 |
| Miscellaneous Fees | $100 - $300 |
| Total Estimated Costs | Varies based on loan |
Budgeting for DSCR Loan Closing Costs
Proper budgeting for DSCR loan closing costs ensures that you are financially prepared for your investment. Here’s how you can plan effectively:
1. Assess the Total Loan Amount
The total loan amount directly impacts several closing costs, such as origination fees and title insurance. By understanding the total loan amount, you can estimate these costs more accurately.
2. Research Fee Estimates
Use the table above as a reference to get an idea of the typical costs associated with each component. Remember that fees can vary based on location and lender policies, so obtaining detailed estimates is crucial.
3. Set Aside an Emergency Fund
Unexpected expenses can arise during the loan process. Having an emergency fund ensures that you can cover any additional costs without disrupting your investment plans.
4. Negotiate Fees Where Possible
Some fees, like origination fees, may be negotiable. Discuss these with your lender to potentially reduce your overall closing costs. Being proactive in negotiations can lead to significant savings.
5. Consider Rolling Costs into the Loan
In some cases, you may be able to include certain closing costs in your loan amount, reducing immediate out-of-pocket expenses. This option can help manage cash flow more effectively, especially if you prefer to keep more capital available for your investment.
Total Cash Needed at Closing vs. Closing Costs
Closing costs are just one part of what you’ll pay. In a refinance, you may also need:
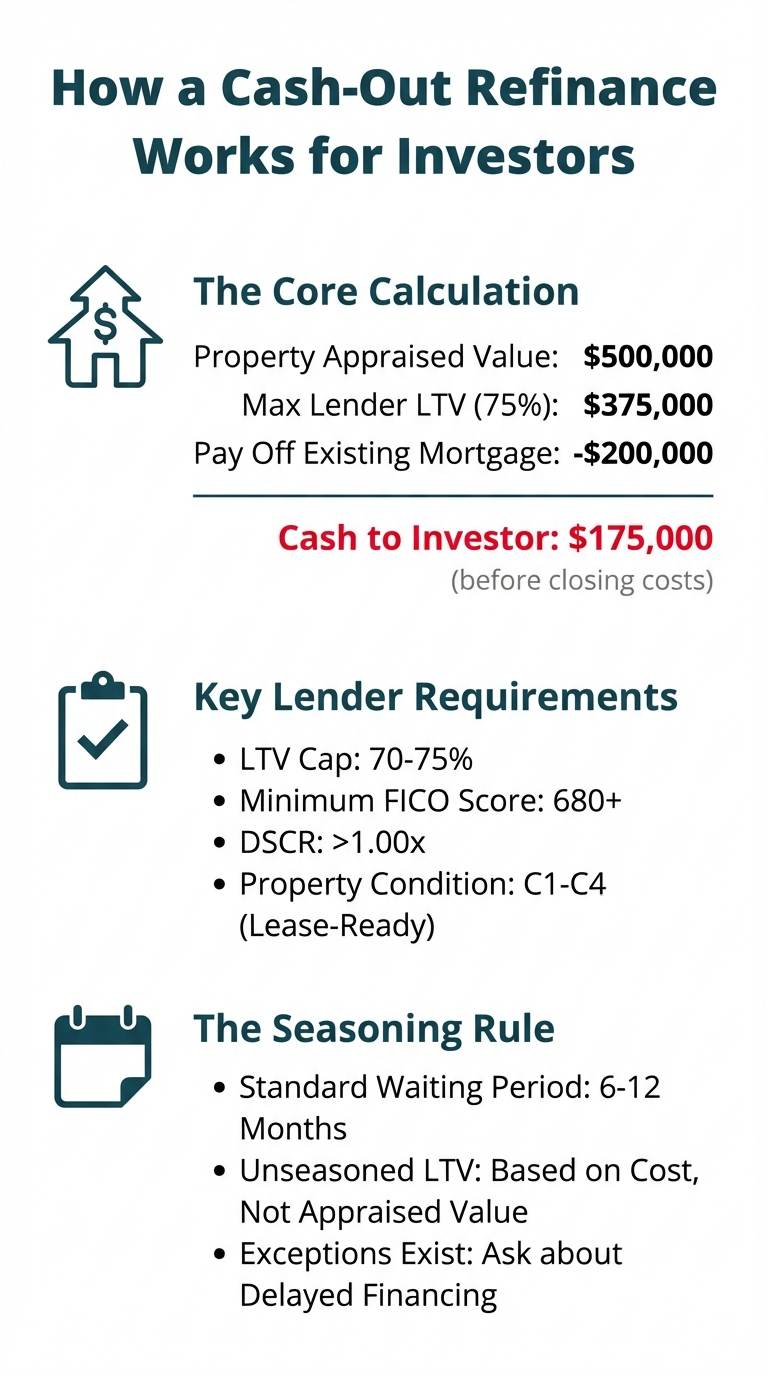
- Enough equity to meet LTV rules (e.g., 25% equity for a cash-out refinance)
- Cash reserves: Some lenders require you to show 3–6 months of PITIA (Principal, Interest, Taxes, Insurance, HOA) in your bank account
So your full “cash to close” could be higher than just fees.
Strategies to Manage DSCR Loan Closing Costs
Effectively managing DSCR loan closing costs can enhance your investment's profitability. Here are strategies to consider:
1. Compare Fee Structures
Always compare quotes from multiple DSCR lenders. Each lender may charge different origination fees, points, and third-party costs. Getting personalized quotes helps you find the best deal.
2. Optimize Your Credit Score
A higher credit score can lead to lower credit report fees and potentially better loan terms, reducing your overall costs. Maintaining a good credit score is essential for securing favorable loan conditions.
3. Choose a Competitive Appraiser
Selecting an experienced appraiser ensures accurate property valuation, potentially lowering appraisal fees and avoiding overpaying for services. Accurate appraisals are critical for fair loan amounts and can prevent unnecessary costs.
4. Utilize Professional Services Wisely
Hiring a reputable attorney and reliable title company can prevent costly legal issues and ensure a smooth closing process. Investing in quality professional services may lead to long-term savings by avoiding disputes and delays.
5. Plan for Long-Term Costs
Consider how closing costs affect your investment's cash flow and plan accordingly to maintain financial stability. Understanding the long-term impact of these costs helps in making informed investment decisions.
6. Leverage Technology and Online Tools
Utilize online calculators and budgeting tools to estimate your DSCR loan closing costs accurately. These tools can help you visualize your expenses and make data-driven decisions.
7. Educate Yourself Continuously
Stay informed about changes in the real estate and lending markets. Continuous education helps you anticipate potential cost changes and adapt your strategies accordingly.
The Importance of Understanding DSCR Loan Closing Costs
Grasping the full scope of DSCR loan closing costs is essential for making informed investment decisions. These costs impact your initial investment and long-term profitability. By thoroughly understanding and planning for these expenses, you can ensure that your investment property financing is both efficient and effective.
Impact on Investment Strategy
Closing costs are part of your initial investment outlay. Accurately accounting for these costs helps in evaluating the true cost of acquiring a property and ensures that your investment strategy remains viable.
Cash Flow Management
Properly budgeting for closing costs prevents cash flow issues post-purchase. Ensuring that you have allocated funds for these expenses helps maintain your investment’s financial health.
Risk Mitigation
Understanding all associated costs minimizes the risk of unexpected financial strain. Being prepared for all expenses allows you to handle unforeseen challenges without jeopardizing your investment.

Common Misconceptions About DSCR Loan Closing Costs
There are several myths surrounding DSCR loan closing costs that can lead to confusion and financial missteps. Let’s address some of the most common misconceptions:
Myth 1: DSCR Loans Have Lower Closing Costs
While DSCR loans offer unique benefits, their closing costs are not inherently lower than other loan types. It's essential to evaluate each component carefully to understand the true cost.
Myth 2: All Fees Are Non-Negotiable
Some fees, such as origination fees, may be negotiable. It's worthwhile to discuss potential reductions with your lender to lower your overall closing costs.
Myth 3: Closing Costs Are the Same for Every Property
Closing costs can vary based on the property's location, value, and the specific terms of the loan. Always obtain detailed estimates for each investment property to avoid surprises.
Myth 4: You Can Ignore Closing Costs in Your Budget
Overlooking closing costs can lead to unexpected financial strain. Always include these costs in your initial investment planning to ensure a smooth transaction.
Myth 5: All Closing Costs Are Fixed
Some closing costs can fluctuate based on factors like loan amount, property type, and market conditions. Understanding which costs are variable helps in more accurate budgeting.
Detailed Breakdown of Each Closing Cost
To further understand DSCR loan closing costs, let's delve deeper into each component:
Loan Origination Fees
Loan origination fees compensate the lender for evaluating and processing your loan application. This fee can vary based on the loan amount, lender policies, and your negotiation skills. It’s essential to understand how this fee is calculated and if there’s room for negotiation.
Appraisal Fees
The appraisal process involves a professional assessor evaluating the property to determine its market value. This ensures that the loan amount is justified based on the property’s worth. An accurate appraisal protects both you and the lender from overextending financially.
Credit Report Fees
Lenders assess your credit history to determine your ability to repay the loan. The credit report fee covers the cost of obtaining this information. Maintaining a good credit score can reduce this fee and potentially lead to better loan terms.
Title Insurance
Title insurance safeguards against potential legal issues related to property ownership, such as undisclosed liens or ownership disputes. It provides peace of mind that the property's title is clear, preventing future legal complications.
Escrow Fees
Escrow services manage the exchange of funds between parties, ensuring that all conditions of the sale are met. This neutral third party handles the disbursement of funds, adding a layer of security to the transaction.
Recording Fees
Recording fees are paid to local government offices to officially document the property transfer and mortgage agreement. These fees ensure that the property’s ownership is legally recognized and publicly recorded.
Survey Fees
A property survey confirms the boundaries of the property, ensuring there are no encroachments or disputes with neighboring properties. This step is crucial for validating the property's exact dimensions and legal boundaries.
Attorney Fees
Legal representation may be necessary to review loan documents and ensure that your interests are protected throughout the transaction. Attorney fees vary based on the complexity of the loan and the services provided.
Miscellaneous Fees
Miscellaneous fees can include a variety of smaller expenses, such as courier services, document preparation, and administrative costs. While individually small, these fees can add up and should be accounted for in your budget.
How to Minimize DSCR Loan Closing Costs
Minimizing DSCR loan closing costs can enhance your investment’s profitability. Here are actionable steps to help you reduce these expenses:
1. Shop Around for Services
While you can’t compare lenders directly, you can shop around for services like appraisal and title insurance. Getting multiple quotes can help you find the best rates and reduce costs.
2. Bundle Services
Some service providers offer bundled packages for multiple services, such as title insurance and escrow. Bundling can lead to discounts and lower overall costs.
3. Negotiate Fees
Don’t hesitate to negotiate fees with service providers. Many fees are flexible, and providers may be willing to lower their rates to secure your business.
4. Reduce Your Loan-to-Value (LTV)
In a refinance, bringing more cash at closing can reduce your loan size. A lower LTV can mean lower fees and possibly better interest rates.
5. Review Loan Estimates Carefully
Thoroughly review your loan estimates to identify any unnecessary fees or errors. Ensuring that all fees are legitimate and correctly calculated can prevent overpaying.
Your loan costs depend on several factors:
- Credit Score: Higher score = lower interest rate and fees
- DSCR Ratio: Stronger rental income = better pricing
- Loan-to-Value (LTV): Lower LTV = better terms
- Property Type and Location: Condos, multi-units, or rural properties may cost more
6. Opt for Electronic Document Signing
Choosing electronic document signing can reduce courier fees and speed up the closing process, potentially lowering some costs.
7. Maintain a Good Credit Score
A higher credit score can result in lower credit report fees and better loan terms, indirectly reducing your closing costs.
8. Utilize Existing Relationships
If you have existing relationships with real estate professionals, such as attorneys or title companies, leverage these connections to negotiate better rates.
Understanding the Timeline of DSCR Loan Closing Costs
The timeline for incurring DSCR loan closing costs typically aligns with the loan application and approval process. Here’s a general timeline to help you anticipate when these costs will arise:
Pre-Approval Stage
- Credit Report Fees: Obtained early in the process to assess your creditworthiness.
- Loan Origination Fees: Often discussed during pre-approval negotiations.
Application Stage
- Appraisal Fees: Scheduled once you’ve made an offer on a property.
- Survey Fees: Required based on the lender’s requirements for property boundaries.
Underwriting Stage
- Title Insurance: Initiated during underwriting to ensure clear property titles.
- Attorney Fees: Engaged to review loan documents and contracts.
Closing Stage
- Escrow Fees: Finalized during the closing process to manage fund disbursement.
- Recording Fees: Paid at the time of recording the property transfer.
- Miscellaneous Fees: Settled as part of the final closing costs.
Understanding this timeline helps you prepare financially and ensures that you have funds available when each cost arises.
Impact of DSCR Loan Closing Costs on Your Investment
DSCR loan closing costs directly impact your investment by affecting your initial outlay and overall financial strategy. Here’s how these costs play a role:
Initial Investment Outlay
Closing costs are part of your initial investment when acquiring a property. Accurately accounting for these costs ensures that your investment budget is comprehensive and realistic.
Cash Flow Considerations
Higher closing costs can affect your cash flow, especially in the early stages of your investment. Proper budgeting helps maintain positive cash flow and ensures that your investment remains financially viable.
Return on Investment (ROI)
Minimizing closing costs can enhance your ROI by reducing the total amount invested upfront. Efficient management of these costs contributes to better profitability over the investment period.
Financing Terms
Understanding and managing closing costs can lead to better financing terms, such as lower interest rates or reduced loan amounts. These favorable terms can significantly impact your investment’s success.
Preparing for Unexpected DSCR Loan Closing Costs
Even with meticulous planning, unexpected DSCR loan closing costs can arise. Here’s how to prepare for and handle these surprises:
1. Set Aside a Contingency Fund
Allocate a portion of your budget specifically for unexpected costs. A contingency fund acts as a financial buffer, ensuring that unforeseen expenses do not derail your investment plans.
2. Conduct Thorough Due Diligence
Thoroughly review all loan documents and requirements to anticipate potential costs. Understanding the full scope of what’s required minimizes the likelihood of unexpected fees.
3. Stay Informed About Market Changes
Market conditions can influence closing costs, such as fluctuations in appraisal fees or changes in local government fees. Staying informed helps you anticipate and adapt to these changes.
4. Communicate with Your Lender
Maintain open communication with your lender throughout the loan process. Promptly addressing any questions or concerns can prevent misunderstandings and unexpected costs.
5. Reevaluate Your Investment Strategy
If unexpected costs arise, reassess your investment strategy to determine if adjustments are needed. Flexibility in your approach ensures that you can adapt to financial changes without compromising your investment goals.
6. Watch Out for Prepayment Penalties
Many DSCR loans have a prepayment penalty if you refinance or pay off the loan within the first 3 to 5 years. These can cost you thousands if you refinance early. Always ask your lender if a prepay penalty applies before starting a new loan.
Leveraging Professional Advice for DSCR Loan Closing Costs
Seeking professional advice can provide valuable insights into managing DSCR loan closing costs effectively. Here’s how professionals can assist you:
1. Financial Advisors
Financial advisors can help you create a comprehensive budget that includes all closing costs, ensuring that you are financially prepared for your investment.
2. Real Estate Attorneys
Attorneys can review loan documents and closing agreements to ensure that all fees are legitimate and that your interests are protected.
3. Mortgage Brokers
Mortgage brokers can guide you through the loan process, helping you understand each cost component and identify potential savings.
4. Real Estate Agents
Experienced real estate agents can provide insights into local market conditions, helping you anticipate and plan for location-specific closing costs.
5. Accountants
Accountants can assist in integrating closing costs into your overall financial plan, ensuring that your investment aligns with your financial goals.

Tools and Resources for Managing DSCR Loan Closing Costs
Utilizing the right tools and resources can simplify the management of DSCR loan closing costs. Here are some recommendations:
1. Online Calculators
Use online calculators to estimate your closing costs based on your loan amount and property value. These tools provide a quick overview of potential expenses.
2. Budgeting Software
Budgeting software like Mint or YNAB can help you track and manage your closing costs alongside your overall investment budget.
3. Spreadsheets
Create detailed spreadsheets to itemize each closing cost component. This allows for better visualization and tracking of your expenses.
4. Professional Networks
Join real estate investment groups or forums to gain insights and tips from other investors on managing closing costs effectively.
5. Educational Webinars and Workshops
Attend webinars and workshops focused on real estate financing to stay informed about best practices for managing DSCR loan closing costs.
Final Thoughts on DSCR Loan Closing Costs
Understanding DSCR loan closing costs is a vital step in securing financing for your investment properties. These costs impact your initial investment and long-term profitability. By being aware of the various fees and implementing strategies to manage them, you can enhance your investment's success and ensure a smoother loan process.
Proper budgeting, strategic planning, and leveraging professional advice are key to effectively managing these costs. By taking control of your DSCR loan closing costs, you set the stage for a profitable and sustainable investment journey.
DSCR Loan Quote

Our mission is to help you build wealth through real estate. Let's grow and optimize your rental property portfolio!
- Get your instant DSCR loan quote today!
- Save big on premiums with our landlord insurance rate shopping service!
- Interested in exclusive investment opportunities? Browse off market properties now!
- Join our Facebook community to stay up-to-date with the latest platform updates and market insights.
- Subscribe to our Youtube channel for our monthly DSCR loan update.

OfferMarket Loans
Check your rate
60 seconds · no credit pull