Understanding DSCR Loans: An OfferMarket Guide for Real Estate Investors
Securing the right financing can be a game-changer for real estate investors, and DSCR loans are quickly becoming a popular choice. These loans, designed to focus on a property's cash flow rather than the borrower's personal income, offer a streamlined path for investors looking to expand their portfolios. Bank of America, a trusted name in the financial industry, provides access to these innovative loan options.
DSCR loans are particularly appealing because they prioritize the property's ability to generate income, making them ideal for seasoned and first-time investors alike. With Bank of America's extensive resources and expertise, borrowers can explore flexible terms and competitive rates tailored to their investment goals. Understanding how these loans work and what Bank of America offers can open doors to new opportunities in real estate.
What Is A DSCR Loan?
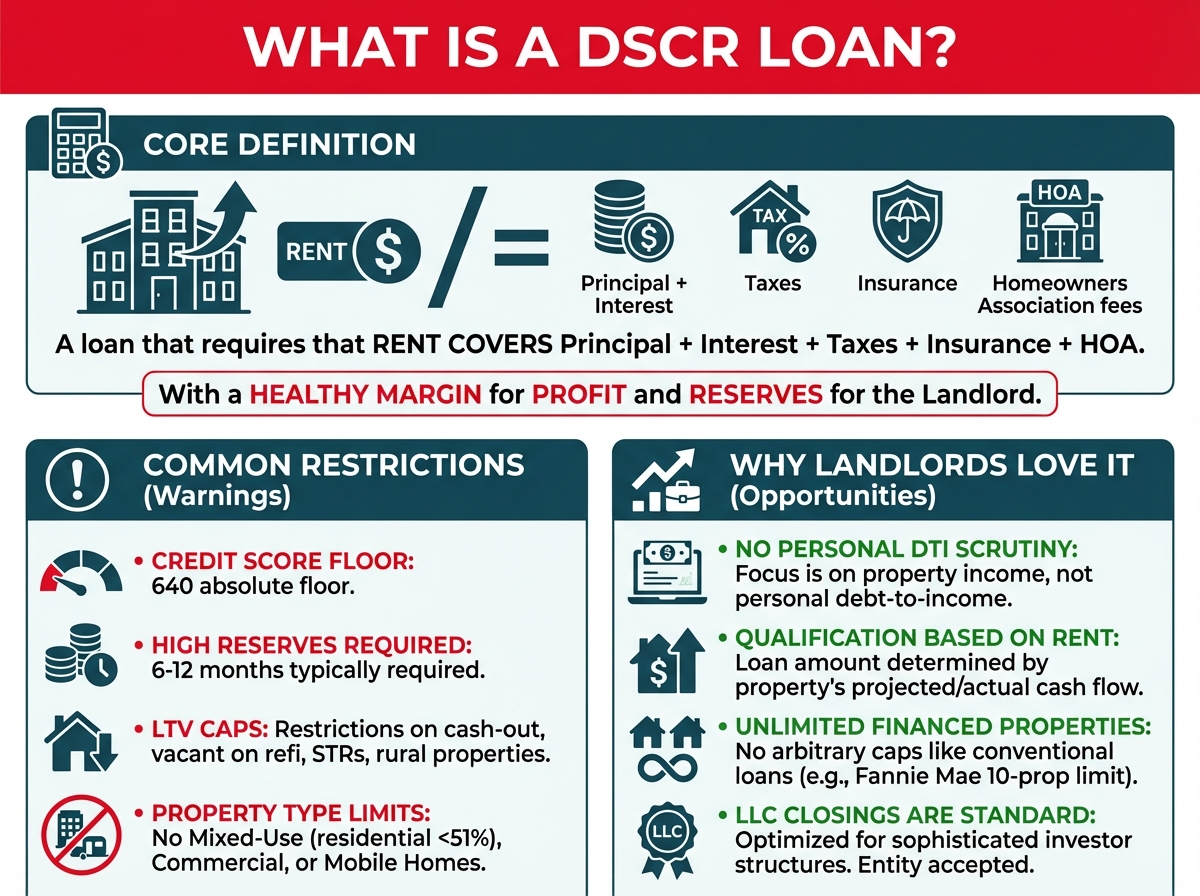
A DSCR (Debt Service Coverage Ratio) loan is a type of financing designed for real estate investors. It primarily evaluates a property's ability to cover debt payments through its cash flow, minimizing reliance on personal income verification.

Understanding DSCR
DSCR measures a property's net operating income (NOI) against its debt obligations. It's expressed as a ratio, such as 1.25, where the income is 1.25 times higher than the debt. Lenders prioritize properties with a DSCR above 1.0, as this indicates sufficient income to cover loan payments. For instance, if a property generates $12,500 in monthly NOI and requires $10,000 for debt payments, its DSCR is 1.25.
- No Personal Income Verification
Lenders assess property cash flow instead of borrower employment or tax returns. This benefits investors with non-traditional income sources. - Flexible Loan Options
DSCR loans offer adjustable rates and terms. Borrowers access tailored solutions based on investment goals. - Wide Property Eligibility
Rental properties like single-family homes, multi-unit buildings, and commercial properties often qualify. - Simplified Qualification
Approval depends on the DSCR meeting lender criteria, reducing the complexity of traditional income-based processes. - Investment-Focused Purpose
These loans target seasoned and first-time property investors aiming to maximize portfolio growth.
Key metrics like the DSCR guide lenders in deciding loan approval and terms. Higher DSCR ratios often secure better rates.

How Property Income Affects DSCR Qualification
Lenders assess the property’s income based on either:
Market rent (via appraisal rent schedule) or
Actual signed lease(s)
This income is compared to the monthly debt payment to calculate DSCR.
Lenders may apply a vacancy factor (usually 5–10%) when estimating gross income.
Properties with DSCR < 1.0 may not qualify or will receive higher rates.
OFFERMARKET’S ACTUAL CRITERIA
OfferMarket DSCR Loan Requirements
Minimum DSCR: 1.0
Credit Score: 660 minimum; 680+ preferred
Entity Type: Must use an LLC or Corporation (no individual borrowers)
Down Payment: 20%–35% (LTV capped at 80%)
Property Type: Non-owner-occupied, income-producing rentals
Minimum Loan Amount: $55,000
Minimum As-Is Property Value: $100,000
Documents Needed:
Operating Agreement, Articles of Incorporation
Appraisal report (including rent schedule)
Soft trimerge credit report for all guarantors
Bank statements (2 months)
About OfferMarket DSCR Loans
OfferMarket provides DSCR loans that let real estate investors qualify based on the property’s rental income, not their personal income. No tax returns, no W-2s, and no employment verification required.
Key features include:
Loan amounts from $55,000 to $2,000,000
Fixed or interest-only terms (30-year fixed options available)
Max LTV: 80% for rate and term, 75% for cash out
Minimum DSCR: 1.0
Minimum credit score: 660–680 (higher scores get better terms)
Eligible property types: Single-family rentals, 2–4 units, condos, townhomes, and short-term rentals
➡ Get an instant quote with no credit pull. Takes 2 minutes.
Benefits Of DSCR Loans From Bank Of America
Bank of America offers several advantages for borrowers using DSCR loans to fund real estate investments. Their loan features focus on flexibility, accessibility, and efficiency, making them ideal for investors.
Competitive Rates
Bank of America provides DSCR loans with highly competitive interest rates. Rates depend on the property's DSCR ratio, with higher ratios qualifying for lower rates. This ensures that properties with strong cash flow are rewarded with cost-effective financing. Both fixed-rate and adjustable-rate options further meet varied investor needs.
Accessible Loan Amounts
Loan amounts range from $100,000 to multi-million-dollar limits, accommodating small and large investments. This wide range makes it easier for investors to finance single-family homes, multi-unit properties, or commercial buildings. Borrowers can scale portfolios without being limited by loan size constraints.
Streamlined Application Process
The application process centers on the property's financial performance, requiring proof of cash flow and a minimum DSCR ratio of 1.0. Bank of America simplifies approval by forgoing personal income verification, ideal for borrowers with non-traditional income. An acceptable credit score of 650 or higher enhances approval potential.
Drawbacks To Consider
While DSCR loans offer significant benefits, certain drawbacks may impact investors depending on their financial circumstances or property goals.
Potential Higher Costs
DSCR loans can come with higher interest rates compared to traditional mortgages due to the focus on the property's income rather than the borrower's personal creditworthiness. Loan fees, such as origination or processing charges, may also increase the overall cost. For example, properties with lower DSCR ratios might incur premium rates since lenders view them as higher-risk investments.
Strict Qualification Criteria
Eligibility requirements for DSCR loans can exclude some investors. Lenders typically demand a DSCR ratio of at least 1.0, proof of consistent property cash flow, and a credit score of at least 650. Properties failing to meet these financial benchmarks may make it difficult to secure approval. Bank of America's DSCR program also prioritizes properties demonstrating robust net operating income, limiting options for underperforming assets or newly-acquired properties without established revenue streams.
How Bank Of America Compares To Other Lenders
Bank of America sets itself apart in DSCR lending through competitive features and specific limitations. Comparing its offerings to other lenders highlights key differentiators and areas for improvement.
Unique Selling Points
- Competitive Interest Rates
Bank of America offers interest rates that favor properties with high DSCR ratios, rewarding borrowers with stronger-performing investments. These rates often compete closely with other major lenders in the market. - Flexible Loan Terms
Loan terms ranging from 5 to 30 years provide borrowers with both short- and long-term investment strategies, a flexibility not all competitors prioritize. Fixed and adjustable-rate options further enhance customization. - Streamlined Application Process
Focusing solely on property cash flow simplifies the qualification process, especially when compared to lenders requiring extensive personal income documentation. This appeals to investors relying on non-traditional income sources. - Wide Loan Ranges
Loan amounts starting at $100,000 and stretching into the multi-million-dollar range cater to diverse investment strategies, ensuring accessibility for both small-scale and large-scale investors. - Higher Interest Rates for Lower DSCR
For properties with a DSCR ratio at or slightly above the 1.0 threshold, Bank of America may impose higher interest rates than other lenders. This makes their loans less attractive for marginally cash-flow-positive properties. - Strict Qualification Criteria
Requiring a minimum credit score of 650 and stringent documentation of cash flow may exclude some investors. Other lenders might offer more lenient qualification benchmarks for borrowers with borderline credit or property income. - Loan Fees
Loan-related fees can elevate upfront costs, particularly in cases where the DSCR ratio falls below optimal thresholds. Competitors with lower associated fees may appeal to cost-conscious investors.
By weighing these factors, real estate investors can better determine whether Bank of America's DSCR offerings align with their financial goals and property performance metrics.

Conclusion
DSCR loans from Bank of America present a valuable opportunity for real estate investors seeking financing based on property performance rather than personal income. With competitive rates, flexible terms, and a focus on cash flow, these loans cater to a wide range of investment needs. While they come with certain limitations, the benefits often outweigh the challenges for those with well-performing properties. Investors should carefully evaluate their financial goals and property metrics to determine if Bank of America's DSCR loan offerings align with their investment strategy.
Frequently Asked Questions
What is a DSCR loan?
A DSCR (Debt Service Coverage Ratio) loan is a loan designed for real estate investors. It evaluates a property's cash flow, not the borrower's personal income, to determine eligibility. A DSCR above 1.0 indicates that the property generates enough income to cover its debt obligations.
Why is DSCR important for real estate investments?
DSCR is crucial because it shows whether a property generates sufficient cash flow to cover its loan payments. Properties with higher DSCR ratios are more likely to secure better loan terms and competitive interest rates from lenders.
Why choose DSCR loans over traditional loans?
DSCR loans prioritize the property’s financial performance rather than the borrower’s personal income or employment history. This makes them an excellent choice for investors with non-traditional income sources or those seeking flexible qualification processes.
Does Bank of America offer DSCR loans?
Yes, Bank of America provides DSCR loans with competitive interest rates, flexible terms, and loan amounts ranging from $100,000 to several million dollars. They focus on the property's cash flow and require a DSCR ratio of at least 1.0.
What types of properties are eligible for DSCR loans?
DSCR loans are available for a variety of property types, including single-family homes, multi-unit residential buildings, and commercial properties. This flexibility suits investors targeting different market segments.
What is the minimum DSCR needed to qualify for a loan?
Most lenders, including Bank of America, typically require a DSCR ratio of at least 1.0. This ensures the property generates enough net operating income to cover its debt payments.
Can I get a DSCR loan with a low credit score?
A credit score of 650 or higher is generally recommended to strengthen your DSCR loan application. While lenders prioritize cash flow, a solid credit history can improve approval odds and lead to better terms.
What are the pros of Bank of America’s DSCR loans?
Bank of America offers advantages such as competitive interest rates, flexible loan terms, high loan amounts, and a simplified qualification process that focuses on property performance rather than personal income.
Are there any drawbacks to DSCR loans?
Potential drawbacks include higher interest rates for properties with low DSCR ratios, increased loan fees, and strict eligibility requirements that may disqualify some borrowers or marginally cash-flow-positive properties.
How do Bank of America’s DSCR loans compare to other lenders?
Bank of America provides competitive interest rates, flexible terms, and a streamlined application process. However, they may apply higher rates for properties with lower cash flow and have stricter qualification criteria compared to some competitors.
Are DSCR loans good for first-time investors?
Yes, DSCR loans are suitable for first-time investors, especially those who lack steady income documentation but invest in properties with strong cash flow potential. They provide flexibility in qualification and repayment terms.
How can I maximize my chances of getting a DSCR loan?
To improve your chances, ensure the property has a strong DSCR (above 1.0), maintain a credit score of 650 or higher, and provide clear documentation of the property's cash flow, such as rental income statements.
Next Steps with OfferMarket
Get an Instant Quote (2 minutes, no credit pull): offermarket.us/loans
Use the DSCR Calculator to see how your rental property stacks up: offermarket.us/blog/dscr-calculator
Explore Fix and Rent Loan Bundles for acquisition + DSCR refi savings
DSCR Loan Quote

Our mission is to help you build wealth through real estate. Let's grow and optimize your rental property portfolio!
- Get your instant DSCR loan quote today!
- Save big on premiums with our landlord insurance rate shopping service!
- Interested in exclusive investment opportunities? Browse off market properties now!
- Join our Facebook community to stay up-to-date with the latest platform updates and market insights.
- Subscribe to our Youtube channel for our monthly DSCR loan update.

OfferMarket Loans
Check your rate
60 seconds · no credit pull